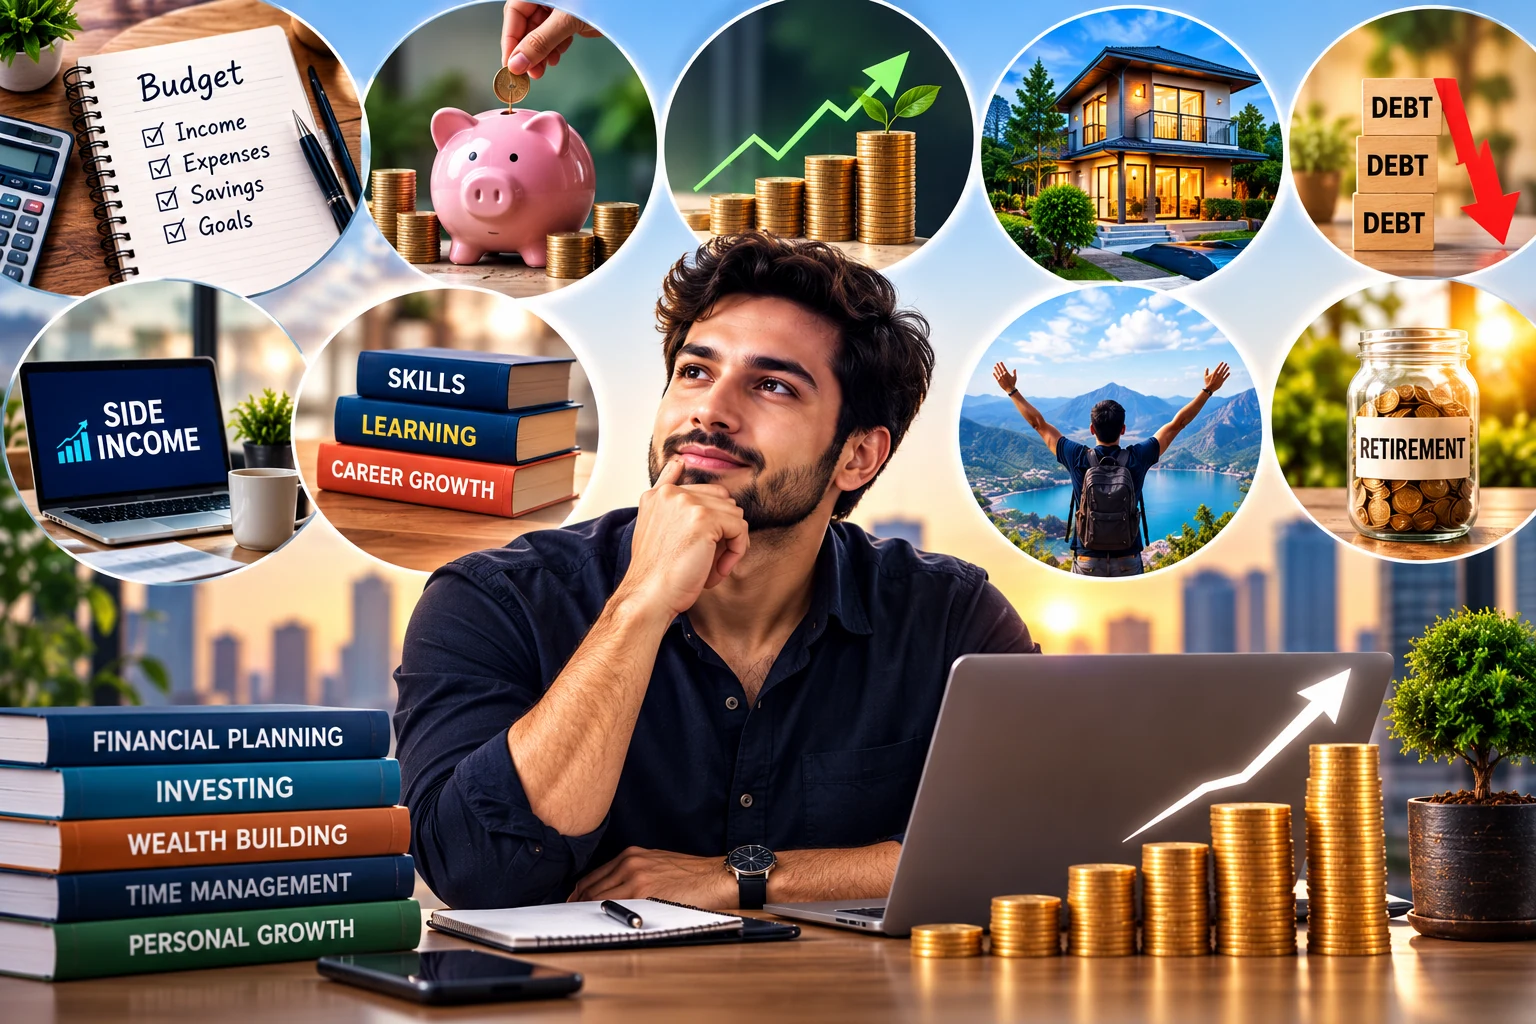
10 Money Habits That Can Help You Build Wealth in Your 30s
Your 30s can be an important period for building financial stability. By this stage, many people have more career experience, greater earning potential, and clearer personal goals than they did in their 20s. At the same time, expenses related to housing, family responsibilities, travel, and long-term plans can make money management more complicated.
Here are ten practical money habits that can help you build wealth in your 30s.
1. Create a Realistic Monthly Budget
A budget helps you understand where your money goes each month. Without a clear plan, small purchases and recurring expenses can gradually consume a large portion of your income.
Start by calculating your monthly take-home pay and listing essential expenses such as rent, groceries, transportation, insurance, and utility bills. Then account for entertainment, shopping, subscriptions, and other discretionary spending.
Review your expenses regularly to identify areas where you can save without sacrificing everything you enjoy. Your budget should reflect your lifestyle and priorities rather than feel like a punishment.
A realistic budget makes it easier to direct money toward savings and investments before spending it elsewhere.
2. Pay Yourself First
One useful financial habit is to set aside money as soon as your salary arrives instead of waiting to see what remains at the end of the month.
For example, you might automatically transfer a portion of your income into a separate savings or investment account. The appropriate amount depends on your income, existing obligations, and financial goals.
Automation reduces the temptation to spend money intended for your future. Even if you can initially save only a small amount, consistency can help you establish a sustainable routine.
As your income increases, consider increasing your contributions rather than allowing every salary raise to become additional spending.
3. Build an Emergency Fund
Unexpected expenses can disrupt even a well-planned financial life. Medical bills, car repairs, temporary unemployment, or urgent household expenses may require money without warning.
An emergency fund provides a financial cushion so you do not have to rely entirely on credit cards or loans when something goes wrong.
A common goal is to save enough to cover three to six months of essential living expenses, although your ideal amount depends on factors such as job stability, dependents, and insurance coverage.
Start with a smaller milestone if necessary. Keep emergency savings somewhere accessible and relatively low-risk rather than placing the entire amount in volatile investments.
4. Control High-Interest Debt
Debt can make wealth-building more difficult when interest charges consume money that could otherwise go toward savings or investments.
Credit card balances and certain personal loans may carry particularly high interest rates. If you have multiple debts, list their outstanding balances, interest rates, and minimum payments.
Continue making required payments on every debt while directing additional money toward an appropriate repayment strategy. Paying the highest-interest debt first can reduce the total interest you pay over time.
Avoid taking on new debt for purchases that do not fit your budget. Before borrowing, consider whether the monthly payments will interfere with essential expenses and future financial goals.
5. Start Investing for Long-Term Goals
Saving money helps preserve funds for upcoming needs, while investing provides an opportunity for long-term growth.
Depending on your goals and risk tolerance, investment options may include diversified mutual funds, exchange-traded funds, retirement accounts, bonds, and other regulated financial products available in your country.
Investments can rise or fall in value, so it is important to understand the risks before committing money. Money needed soon for rent, emergencies, or near-term purchases generally should not depend on volatile market performance.
Your 30s may provide several decades for long-term investments to potentially grow, making consistency and patience especially valuable.
6. Avoid Lifestyle Inflation
Lifestyle inflation happens when spending increases alongside income. A promotion might lead to a more expensive car, a larger home, frequent dining out, or additional subscriptions.
Enjoying the rewards of career progress is perfectly reasonable. The problem arises when every increase in income is immediately absorbed by higher expenses.
When you receive a raise or bonus, consider dividing the additional money between financial goals and personal enjoyment. This approach allows your lifestyle to improve while preserving opportunities to build wealth.
Keeping some expenses stable as your earnings increase can significantly improve your ability to save.
7. Invest in Your Skills and Career
Your earning potential is an important part of your financial future. Developing valuable skills can help you qualify for better roles, negotiate higher compensation, or explore additional career opportunities.
Consider professional certifications, practical courses, communication skills, technical training, or industry-specific knowledge that aligns with your goals.
Before paying for expensive training, research whether employers value the qualification and whether the expected benefits justify the cost.
Career development can also include networking, improving your résumé, learning negotiation techniques, and reviewing your progress regularly.
Investing in yourself may not produce immediate financial returns, but it can create opportunities over time.
8. Protect Your Finances With Appropriate Insurance
Building wealth also means protecting what you have accumulated. A major medical expense, accident, or unexpected loss can place considerable pressure on your finances.
Review the types of insurance relevant to your circumstances, including health, vehicle, home, and life insurance where appropriate.
Life insurance may be particularly important if other people depend on your income or if you have significant financial obligations. The amount and type of coverage should reflect your needs rather than assumptions or sales pressure.
Read policy exclusions, waiting periods, deductibles, and coverage limits before purchasing a policy. Insurance should complement your financial plan, not replace savings or responsible money management.
9. Set Clear Financial Goals
Financial goals give your money a purpose. Instead of simply hoping to become wealthier, identify what you want your finances to accomplish.
Your goals might include buying a home, preparing for children’s education, starting a business, paying off debt, or building a retirement fund.
Assign each goal a target amount and a realistic timeline. Then estimate how much you need to save or invest regularly to make progress.
Separate short-term goals from long-term ones because they may require different financial strategies. Review your goals annually and adjust them when your circumstances change.
10. Review Your Finances Regularly
Financial planning is not something you complete once and forget. Income, expenses, responsibilities, and personal priorities change over time.
Set aside time each month to review spending, savings, debt balances, and progress toward your goals. Once or twice a year, consider reviewing your insurance coverage, investment allocation, and retirement plans.
Look for patterns rather than worrying about every small transaction. If you consistently overspend in a particular category, make a realistic adjustment.
Regular reviews help you identify problems early and make thoughtful decisions instead of reacting to financial pressure.